

VOL. 04 · 30TH APRIL 2026
Paul Gibbons · Paul Gibbons Advisory
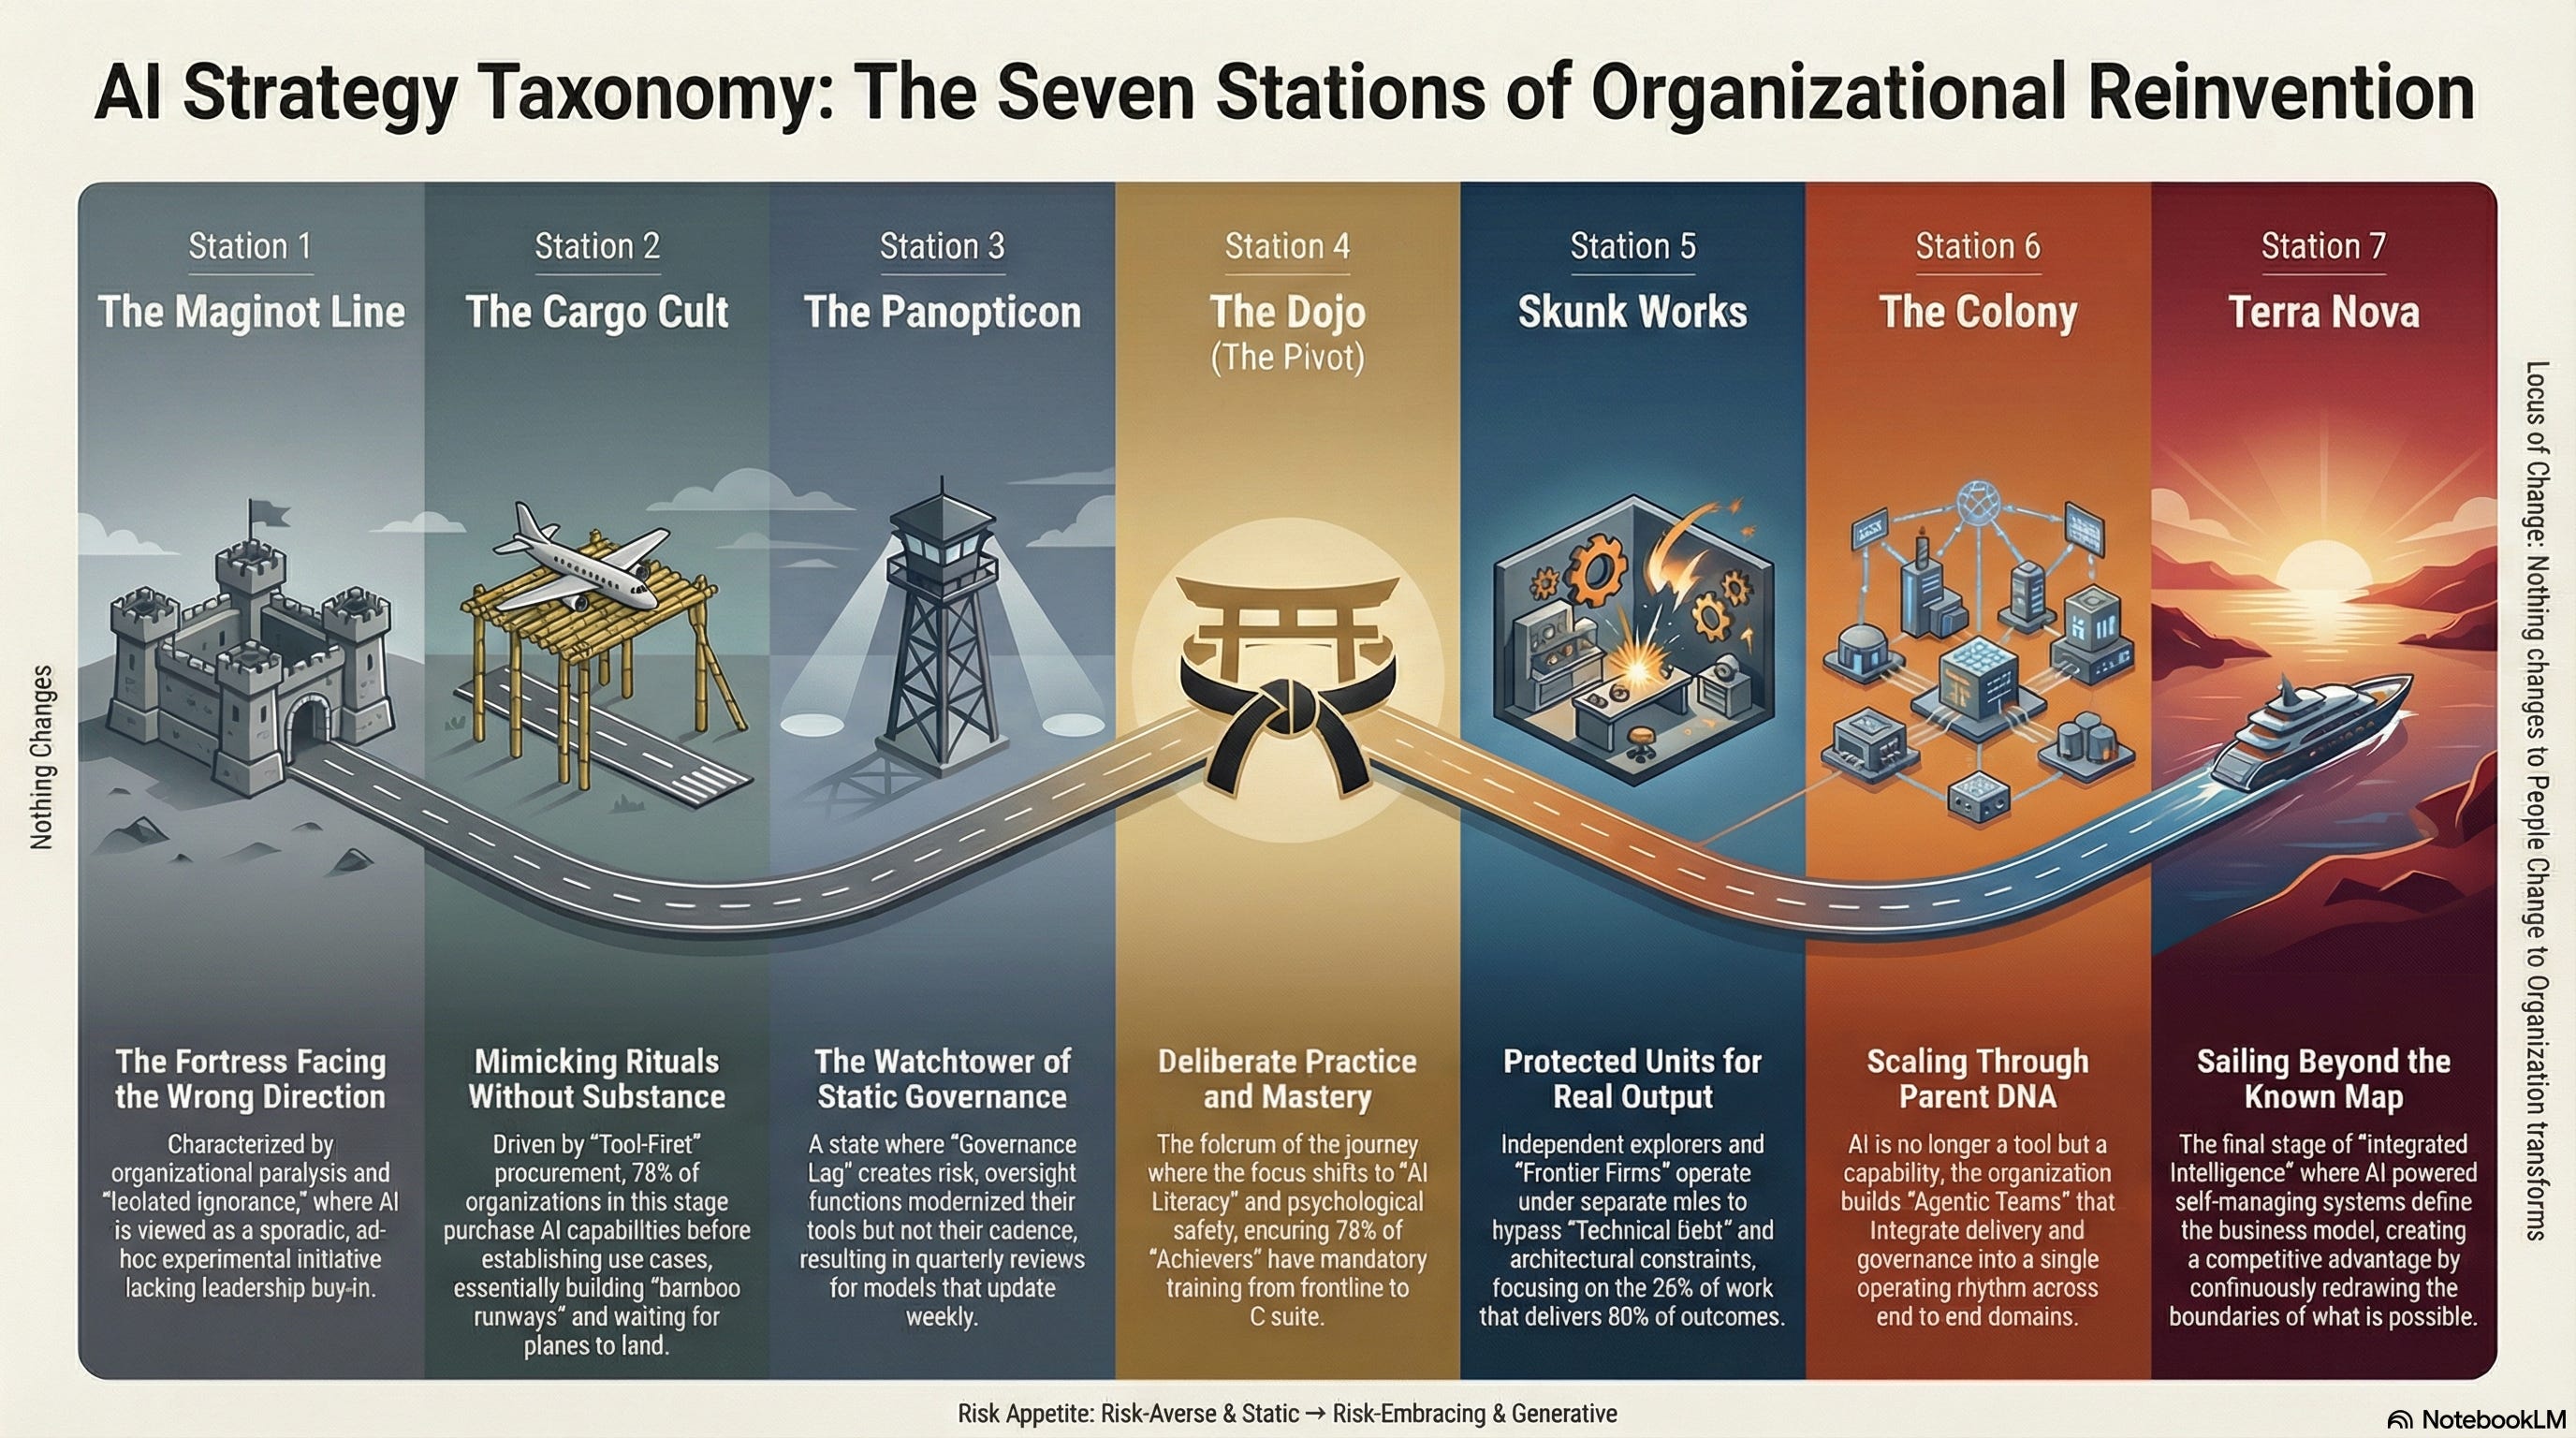
The old enterprise logic, the Coase model of the firm, suggested that in-house expertise entailed fewer frictions. That is demonstrably false today. The gap between insight and execution has dropped to near zero — a talented innovator inside a business may face 9-month enterprise approval frictions; entrepreneurs and microenterprises can ship better in 9 days.
The question we will be debating for the next ten years is whether “economies of scale” logic still holds, or whether modern enterprises are “economies of friction” or more harshly, as I write, anti-innovation machines.
And (as you will read below), my reading of the data is that the gap between slower adopters and folks at the frontier is widening. “Power users” and “power-enterprises” are using AI to learn AI, using AI to deploy AI, and have wrangled the data and infrastructure challenges that were such a pain in 2025.
What makes AI the most fascinating thing I’ve ever studied is its multi-dimensionality — from math and models, to tools, to markets, to ethics, to governance, to neuroscience, to business strategy and design. Keeping up with even one dimension is a full-time job — but keeping sight of the whole is what business leaders must do.
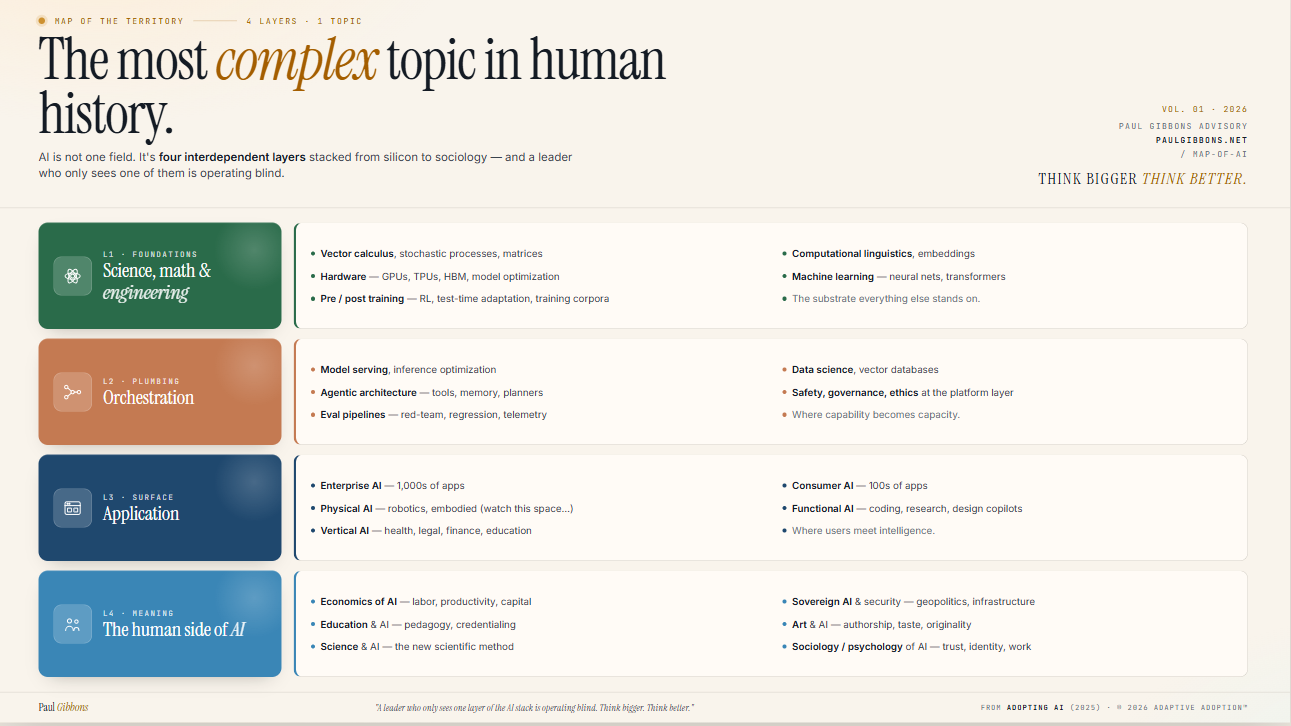
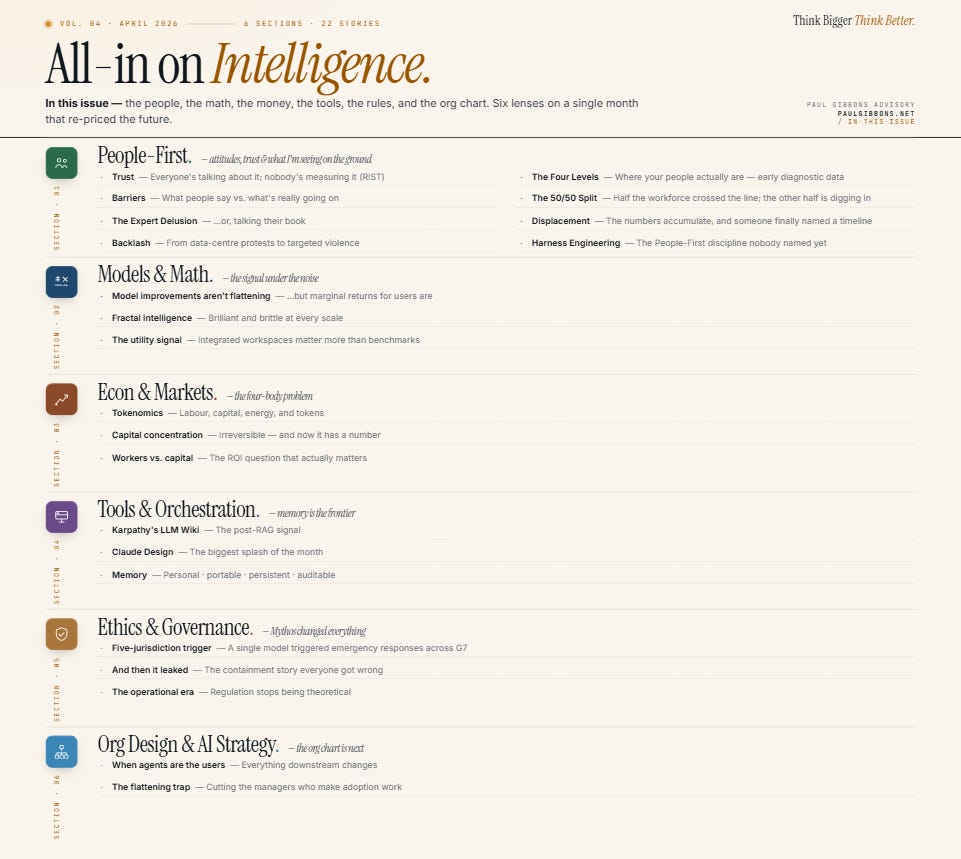
Accordingly, here is what we cover, section by section:
Everything I write stays free. Always will be. But if you want to back the work — $5/month, or $25/year right now (75 percent or so off until 1st of May). For the price of a business book, you get access to all my books via the Corpus (in whatever language) and these monthly roundups.
Back the work → https://thinkbiggerthinkbetter.substack.com/23601d84
SECTION 1: PEOPLE-FIRST (tm) — Attitudes, Trust, and What I’m Seeing
“The gap between thought and action, between belief and will, prevents us from solving our most pressing individual and societal problems.” (The Science of Organizational Change)
People-first is increasingly recognized not just as an ethical statement, but as a technical necessity. Hedge fund Parker Gale has recently picked it up; and McKinsey claim “nearly 60% of respondents cite knowledge and training gaps as the primary barrier to implementing responsible AI practices — up from ~50% the previous year.”
1.1 Everyone started talking about trust. As the Chinese say, “Talk doesn’t cook rice.”
April was the month trust became a consulting buzzword. McKinsey published on it. Edelman’s Trust Barometer flagged AI trust as a standalone metric for the first time. We taught it in our leadership programs starting in 2004, and finally, a friend persuaded me to publish a whitepaper on our work. Read the trust whitepaper →
The problem: “we need to build trust” is the organisational equivalent of “we should exercise more.” It’s true, unfalsifiable, and changes nothing.
What’s missing is measurement. Trust in AI isn’t a single variable — it’s at least four: Reliability, Informativeness, Safety, and Transparency (RIST). Each can be independently calibrated, independently miscalibrated, and independently diagnosed. Undertrust is as costly as overtrust — the team that won’t touch the tool and the team that ships unreviewed AI output are both failing, in opposite directions.
The RIST Trust Diagnostic is FREE and live on the Adaptive Adoption website
It’s open-source and takes five minutes.
If your organisation is “talking about trust,” ask whether anyone has measured it.
1.2 The Four Levels: where your people are
“Learning AI is more like carpentry than calculus.” (March AI briefing)
We launched the AI Mastery diagnostic last week. The sample is small (n=21, self-selected, skewed toward leaders in our network) — but the distribution is already instructive:
User (43%) — can operate AI tools; cannot evaluate output quality or design workflows
Practitioner (19%) — beginning to integrate AI into daily work; judgment still developing
Builder (24%) — designing AI-augmented workflows; can evaluate and iterate
Architect (14%) — shaping organisational AI strategy; teaching others
Of course, this is an early sample - but if it were skewed, my guess is that it would be heavily skewed toward overestimating rather than underestimating capability. Why? It is a self-report and people generally assess themselves as more able than they are, and second, it is people connected to me, who tend not to be hard skeptics.
The question for every enterprise: where do you need your people to be? If you need Practitioners and you have Users, the gap is behavioural, not informational.
Training won’t close it. Leadership modelling will.
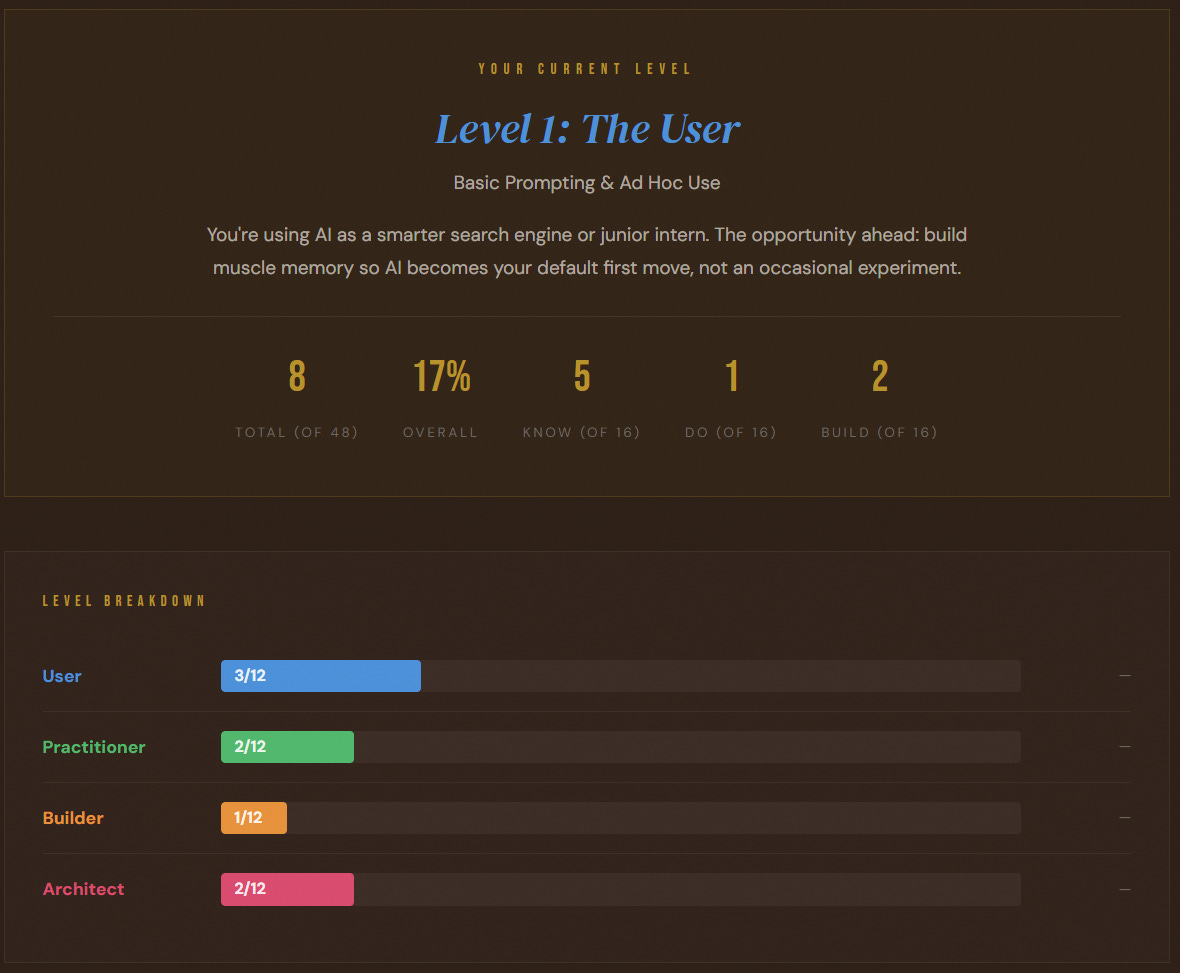
Not where you want your people to be. Where are they?
1.3 What people say their barriers are — and what that really means
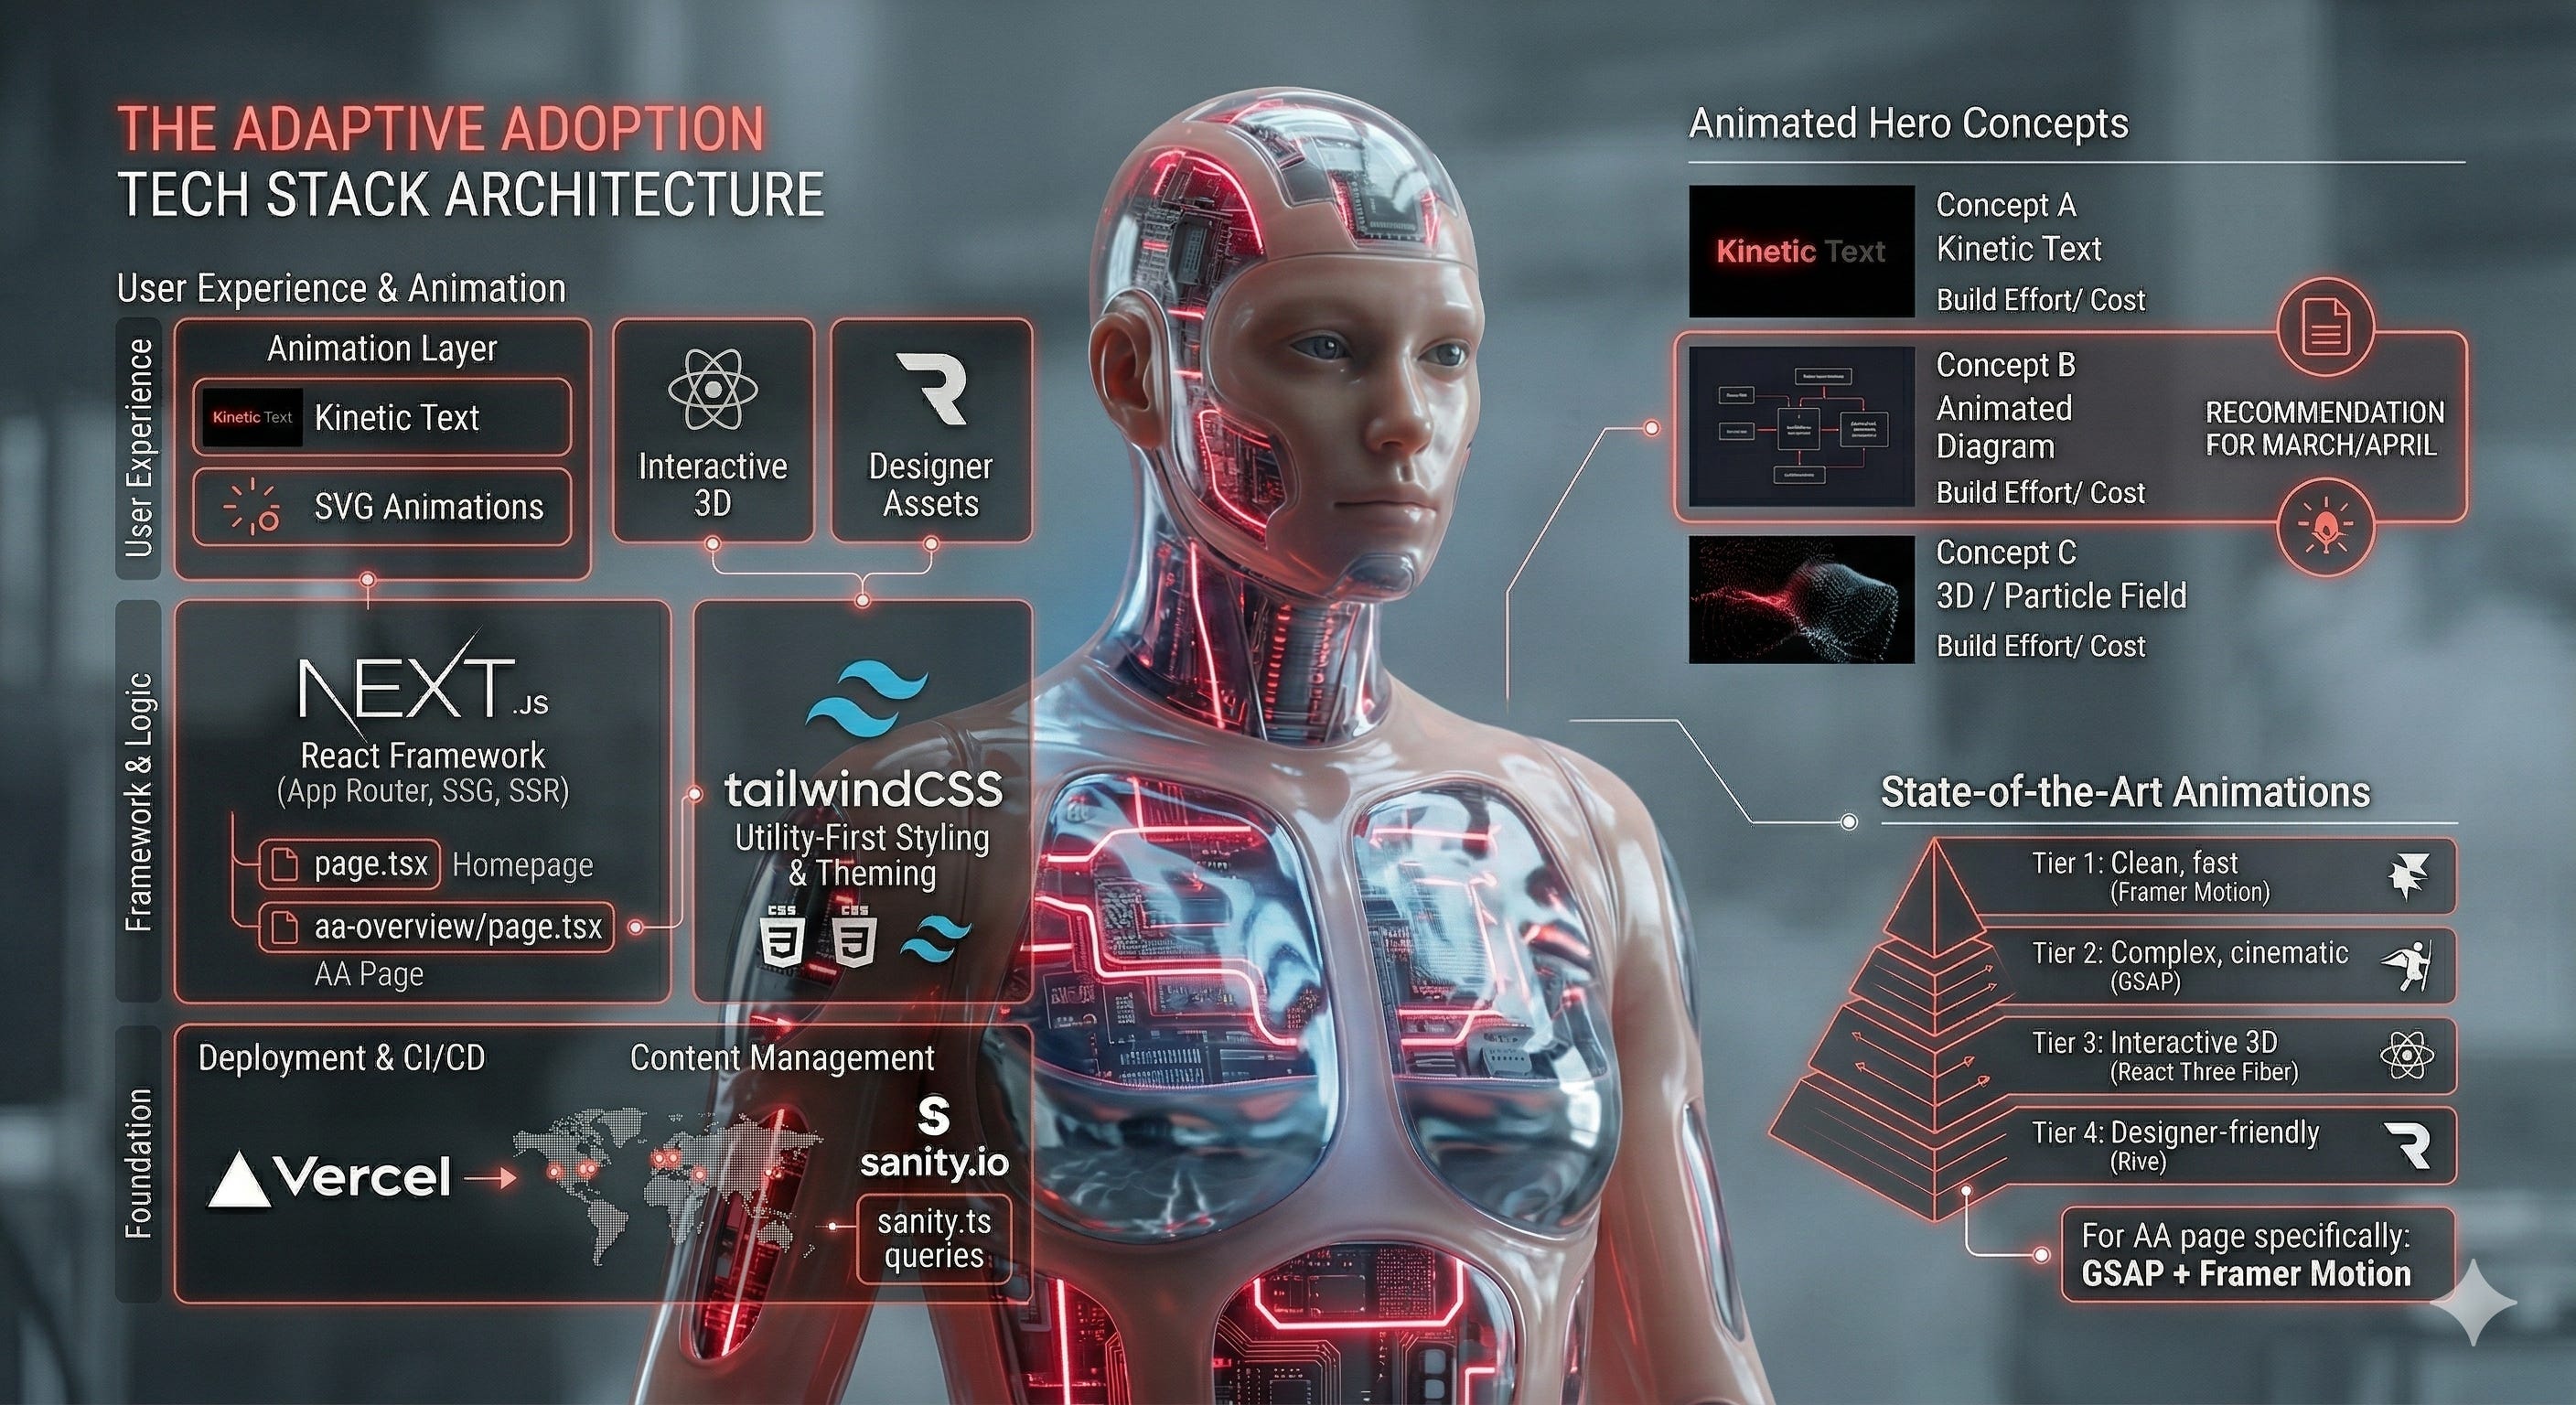
Non-coders are able to build complex architectures. Above is one of mine. But can they in practice - enterprises would block that whole stack.
The enterprise data is consistent across Gallup, BCG, and PwC this month: the top self-reported barriers to AI adoption are time (”I don’t have time to learn”), training (”nobody’s shown me”), and permission (”I’m not sure I’m allowed to”).
These are not technology barriers. They are leadership barriers dressed in operational language.
87% of organisations say they prioritise workforce upskilling. But 57% of executives expect humans to manage and direct AI agents — a competency almost nobody is training for.
46% of non-users say they prefer doing things the old way. 40% cite ethical opposition, privacy, or disbelief. These are not irrational — they are rational responses to absent leadership signals.
PwC’s April study quantified the cost of shallow integration: 74% of AI’s economic gains are captured by 20% of companies. The 20% redesign workflows around AI. The 80% overlay AI on existing processes and wonder why it doesn’t stick. This is the Adaptive Adoption thesis in data form: adoption is a change problem, not a technology problem.
1.4 The 50/50 split — and why it’s more interesting than it sounds
Gallup Q1 2026 (n=23,717): 50% of US employees now use AI at work. First time at this milestone. Generative AI reached 53% population-level adoption in three years — faster than PCs or the internet.
First of all, folks who follow me know I think self-reports are close to worthless — in this case, “what does ‘use’ mean?” I used AI in 2023; I use it now. From light occasional research then, to it being integrated in 100 percent of what I do, including building my own LLM at home, relearning coding, and one dozen AI tools in active weekly use (including 4 frontier model LLMs.)
I’m aware this probably horrifies well over half of you.
Why did I do this? Because to have any chance of helping clients navigate this kind of complexity, I felt I had to have a visceral, embodied sense of what it could do, and what the frustrations are. I also had to feel, and I do, the joy of setting a few agents running, going to the gym for an hour, and coming back to excellent work products. And for senior leaders, I think this is vital — you need to dig in and share the joys and pains your AI strategy visits upon staff. (And I daresay with modest effort, you might just save yourself 5-10 hours a week.)
There are better surveys, such as the AI Daily Brief monthly survey, which is more granular “how many large language models do you use?” or “do you even code bro?” or “are you building agentic workflows?” (The latter are what I call “use”.)
And Gallup’s data exposes the gap: 50% say they “use” AI, but only 1 in 10 say it has fundamentally transformed their workplace. That’s a lot of dabbling dressed up as adoption.
But stats say a little something: 50% do means 50% don’t.
The Gen Z paradox is the sharpest version: the most digitally native generation is simultaneously the most sceptical of AI and the most willing to use it in unsanctioned ways. Gallup’s February–March 2026 data: the share of Gen Z who describe themselves as excited about AI fell from 36% to 22% in one year. The share who describe themselves as angry rose from 22% to 31%. Bloomberg ran this on April 19; Fortune ran a piece on April 8 headlined “Gen Z workers who fear AI will take their job are actively sabotaging their company’s AI rollout.” Read that headline again.
The enterprise implication: monolithic adoption strategies are dead.
And here is one of the grave change management flaws — one-to-many, “sheepdip” approaches target the “average” too often. But what if the distribution is bi-modal? (Two humps not one if you slept during stats class.)
You can’t design a single training programme for a workforce where one cohort is angry and sabotaging and another is building agents at home.
Adaptive Adoption starts with diagnosis — which is why the tools in 1.1 and 1.2 exist.
1.5 The expert delusion — or, talking their book
The expert-public perception gap has become a chasm: Stanford’s recent 400-page tome suggest that 73% of US AI experts view AI’s job impact positively; only 23% of the public agrees — a 50-point gap. Similar divides exist on the economy (69% vs. 21%) and medical care (84% vs. 44%).
The experts are smoking crack — or as we used to say in the markets, “talking their book.”
Exhibit A — Muskian economic growth forecasts:
“Double-digit growth... is coming within 12 to 18 months.”
And as if that were a low-ball guess: “Triple-digit is possible in about five years.”
For context: the OECD projects US real GDP growth at roughly 1.5% for 2026. (And depending on whom you ask, and what they count, AI may be all of that and then some. This is contested territory, but in my view, auspicious names such as Goldman Sachs have it very wrong.)
In 2025, I estimated total AI contribution to the economy at $2 trillion — that includes the full stack (land acquisition, construction, electrical grid upgrades, cooling systems, fibre, the chip supply chain’s domestic portion, cloud services, enterprise software, consulting, training, hiring, the entire SaaS layer built on top.) The $700B capex figure that gets cited is just the top 5-7 hyperscalers’ direct spend. It doesn’t capture the construction crews building data centres in Iowa, the utilities upgrading substations, the HVAC contractors, the legal and permitting work, the enterprise IT teams retooling, the consulting firms staffing AI practices, or the thousands of startups burning through venture capital.
No general-purpose technology in history — not electrification, not computing, not the internet — has produced double-digit GDP growth in its first decade of deployment. For more than a century, U.S. real GDP growth has lived in the low single digits. Musk’s prediction isn’t optimistic; it’s at best early, at worst delusional.
His thinking is emblematic of what I call “naive solutionism” — technology as panacea. But technology hits human systems which respond on decades-long time scales. And consider this thought-experiment: how many of the world’s problems are failures of smarts? Could we think our way out of poverty? Out of climate change? In businesses, how many of the problems are problems that hiring a few Einsteins would solve? None. Workplaces don’t have Einstein-shaped holes in them — so they end up handing Einstein a shovel — like asking Einstein to summarize some emails, or manage a spreadsheet.
Meanwhile, the serious analysts converge on displacement but diverge on recovery. The classical Ricardian pattern — technology destroys jobs, then creates new and better ones — is the J-curve optimists invoke. Amodei at Anthropic broadly holds this view, with caveats about timeline and transition pain. Acemoglu (Nobel 2024) is more pessimistic: his published estimates suggest AI adds a modest ~0.5% to GDP over a decade, with gains captured narrowly — not the broad-based recovery the J-curve implies. Imas at Chicago Booth, presenting on Bloomberg Odd Lots, offered the sharpest formulation: AI may be “categorically different” from prior general-purpose technologies, meaning the historical pattern where new jobs replace displaced ones may simply not hold. They agree the descent is coming. They disagree on whether the curve bends back up, how far, and for whom. The pundits promising sunlit uplands are not the ones building transition plans. The people-first question isn’t whether disruption is coming. It’s whether your organisation has a plan for the humans in between.
1.6 The displacement numbers accumulate — and someone finally put a timeline on it
Q1 2026: 345,000 jobs eliminated as profitable companies redirect salary budgets to AI. Software developer employment for ages 22–25 dropped nearly 20% since 2024. Women constitute 86% of the most vulnerable worker cohort. AI-skilled employees earn 56% more than peers — the premium widens as the entry path narrows.
Then Dario Amodei put a concrete timeline on it: “a significant proportion” of entry-level finance, consulting, and tech positions could vanish within 1–5 years. This is the most specific displacement forecast from a frontier-lab CEO to date.
Bloomberg Odd Lots featured Alex Imas from Chicago Booth, presenting survey evidence that economists, AI specialists, and superforecasters are converging: faster AI progress correlates with lower employment. AI may be “categorically different” from prior general-purpose technologies — meaning the historical pattern where new jobs replace displaced ones may not hold. The Overton window has moved. Leaders who dismiss displacement as “Luddite anxiety” are now behind the industry’s own positioning. OpenAI published a policy paper proposing robot taxes and a 32-hour workweek. When the company most aggressively scaling frontier AI is proposing redistributive mechanisms, the question isn’t whether disruption is coming — it’s whether your organisation has a transition plan.
1.7 Backlash: from data-centre protests to targeted violence
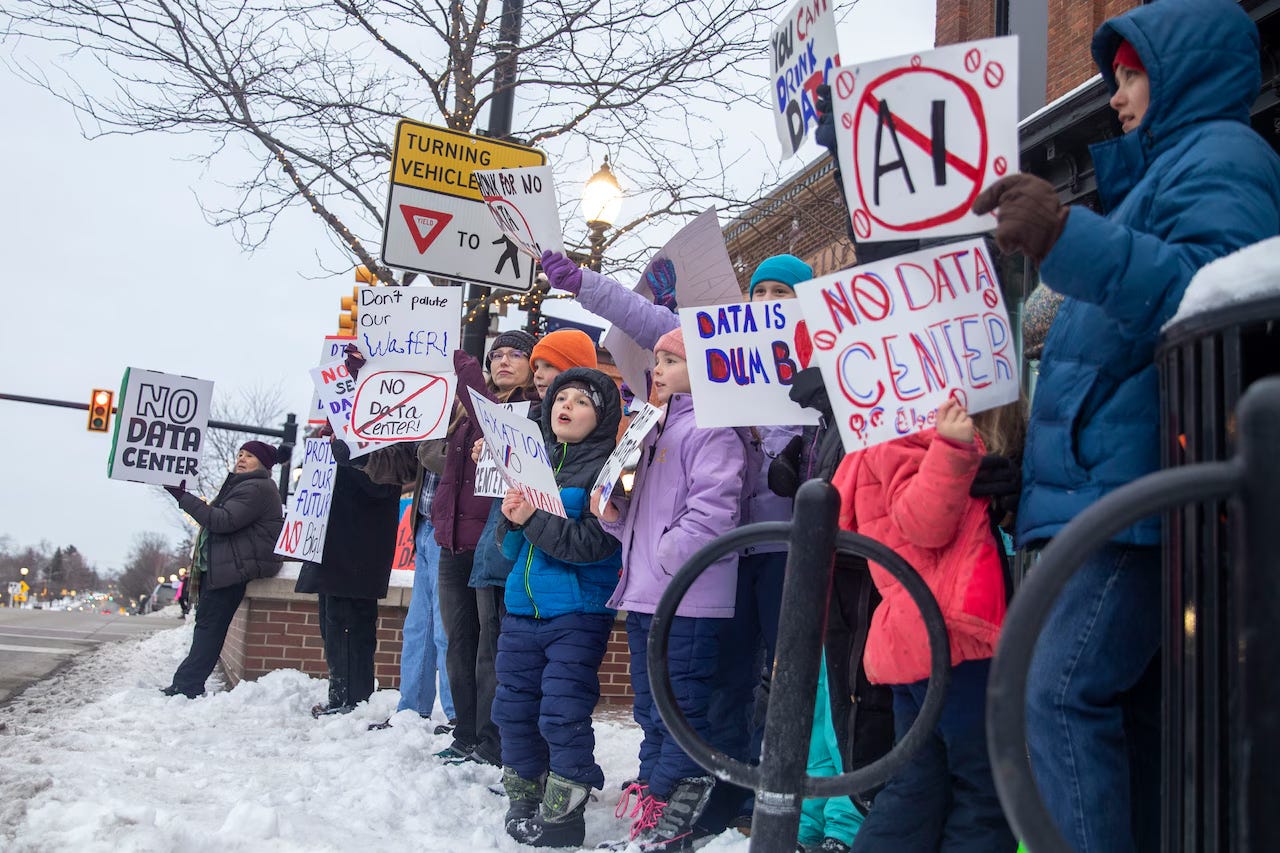
Data-centre protests intensified worldwide in April, uniting bipartisan coalitions over environmental and energy concerns. Maine passed the first-in-the-nation data-centre moratorium. OpenAI paused Stargate UK, citing energy costs among the highest globally. With a US election coming, being anti-AI will be the new populist shibboleth — right and left. NIMBYs at work — three planned Wisconsin data centres would add almost 10 percent to the state economy — but at what cost to the environment and domestic electricity prices?
Then it got darker. Molotov cocktails and gunfire targeted Sam Altman’s San Francisco home (April 13–15). The suspected attacker — a 20-year-old community college student — cited AI extinction risk. Bloomberg’s podcast: “Why the AI Backlash Is Only Going to Get Worse.”
This is no longer a communications problem. It’s a societal legitimacy problem. And it connects to the trust gap in 1.1: when institutions fail to measure and demonstrate trustworthiness, the vacuum fills with fear.
And this is yet another reason why traditional change management isn’t suited to AI — nobody ever hoisted a placard against SAP or Excel rollouts. If a chunk of your workforce is actively hostile, that isn’t a problem fixed with lofty words from the CEO.
And while models are 300x more efficient, token use is expanding faster than that. Inference costs for fixed-capability models have collapsed — roughly 280x for GPT-3.5-level performance in under two years — but that has not reduced total compute pressure. It has expanded the addressable market for intelligence. Cheaper tokens create more tokens: longer contexts, agent loops, multimodal generation, always-on copilots, synthetic data, and reasoning-time computation. The result is not efficiency replacing infrastructure demand, but efficiency making vastly more demand economically possible.
1.8 Harness engineering is the People-First discipline nobody named yet
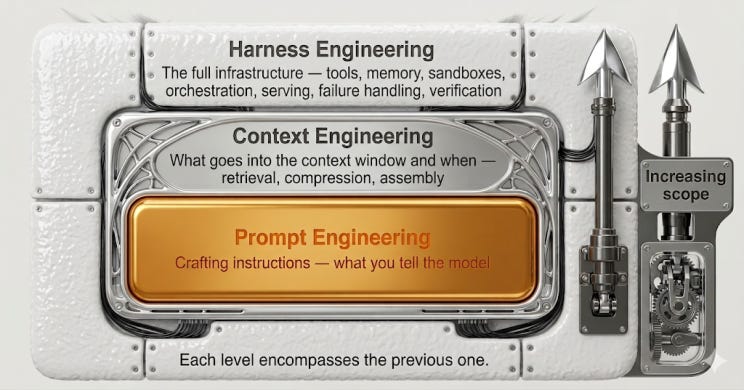
Prompt engineering: 2024. Context engineering: 2025. Harness engineering 2026.
Prompt engineering is so 2024 — harness engineering is what matters more today.
The biggest conceptual shift of the month: Agent = Model + Harness.
The harness is everything that wraps around an AI agent: the tools it can access, the guardrails that keep it safe, the feedback loops, the observability layer. If 2025 was the year of the agent, 2026 is the year of the harness. The industry discovered, painfully, that building an agent is the easy part. Making it reliable, cost-predictable, and safe in production is where the real engineering happens.
The uncomfortable truth: the harness is governance. It’s trust calibration made operational. It’s decision rights encoded as constraints. It’s the Behavioral Governance framework expressed in system prompts, eval suites, and permission boundaries. The people who design harnesses are doing organisational design whether they know it or not.
Anthropic published on context engineering in April — treating context as a first-class system with its own architecture, lifecycle, and constraints. It’s an important contribution. But I’d argue it’s already been superseded. Context is one layer of the harness; harness engineering is the whole discipline. It includes context, yes — but also tool selection, guardrails, feedback loops, observability, permission structures, and governance. The right harness determines whether an agent produces value or chaos. That’s not a technical problem. It’s a leadership problem.
SECTION 2: MODELS & MATH — The Signal Under the Noise
“The engine is not the car. The most powerful model in the world is useless without the harness, the context, and the human judgment that tells it where to drive.”
2.1 The biggest model news is that model news doesn’t matter to most people
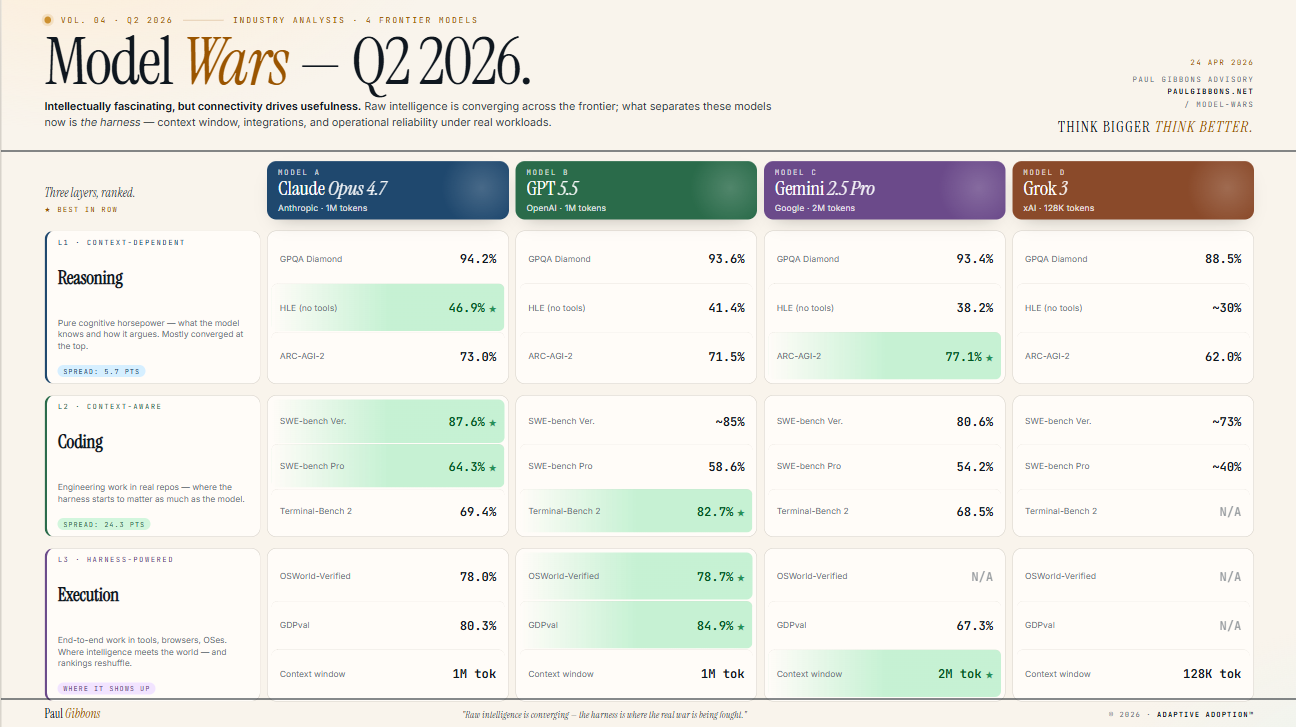
Model capabilities aren’t flattening — METR’s Time Horizon benchmark shows AI improving at ~10× per year, with a doubling time of about 4.3 months. Opus 4.7 launched 16th April; ChatGPT dropped 5.5 on 24th April. DeepSeek V4 dropped. Qwen, Zhipu GLM-5.1, Gemma 4 — the open-weights ecosystem keeps delivering. Mythos (see below) was deemed too powerful for general release.
But here’s what matters: the marginal returns for people and enterprises from model improvements are flattening. The top four models on the Arena Leaderboard are separated by fewer than 25 Elo points. For most enterprise users, the difference between this month’s frontier model and last month’s is invisible. And many enterprises can’t use them anyway — banned by policy, blocked by procurement, or locked behind approval chains that move slower than release cycles.
The model glow-ups are noise. The signal is what happened around the models.
And here is what we might be talking about in 2030. How Microsoft screwed the pooch.
The conspicuous absence from any serious benchmark comparison is Microsoft Copilot. A company with 400 million Office 365 seats had a two-year head start on enterprise AI integration — arguably the largest distribution moat in technology history — and squandered it by treating AI as a pricing lever rather than a product revolution. A $30/seat/month tax bolted onto products that didn’t fundamentally change. The harness was an afterthought; the revenue model was the product. Meanwhile, the competitors who took harness design seriously — Claude’s integrated workspace, Gemini’s 2M token context — are shipping tools that actually reimagine how work gets done. Never has a moat been so quickly pissed away, and the lesson for every enterprise leader is instructive: distribution without genuine product transformation is just a more expensive version of the status quo.
2.2 What I call “fractal intelligence” — brilliant and brittle
The Stanford HAI term is “jagged intelligence.” I prefer fractal — the pattern of brilliance and brittleness repeats at every level of magnification. Gemini Deep Think won a Gold Medal at the International Mathematical Olympiad. The same class of models reads analog clocks with 50.1% accuracy. AI scored below 20% on replicating astrophysics papers. PhD-level experts still outperform the best AI agents by 2× on complex multi-step tasks (Nature/Stanford HAI).
The consensus reads that as reassuring: “see, humans still win.” I read it the other way. It takes a PhD to outrun an LLM. Unless someone has doctoral-level domain knowledge, they are running in second place. That is not a story about human superiority. It is a story about what the floor of competence just became — and most of your workforce is below it.
This reinforces the augmentation thesis and undercuts the automation thesis, but not in the way most people frame it. The fractal pattern means you can’t predict from capability benchmarks where an AI will be useful in your context. The only way to know is to test it — which requires the kind of experimentation infrastructure that Section 1 describes. The organisations capturing value are the ones with the manager-multiplier effect, the trust calibration, and the permission structures that let people try.
2.3 The utility signal: integrated workspaces stole the march
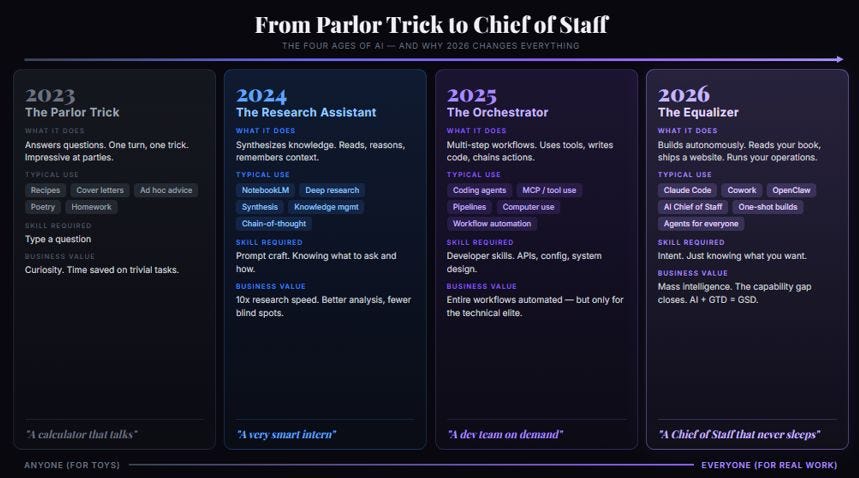
In 2023, AI was cute. In 2024, it was clever. In 2026, it got interesting.
What did matter in April for actual users: Claude stole a massive march with an integrated workspace. Cowork, Code, Projects, scheduled tasks, persistent memory, Claude Design (which is “lit”)— these aren’t model improvements. They’re harness improvements. They reduced the friction between “I have an idea” and “I have a working output” more than any benchmark gain this year.
Claude Design in particular (Figma stock fell 7.28% on announcement day) demonstrated something important: the competitive moat is no longer model quality. It’s the completeness of the system wrapped around the model.
The harness, again.
SECTION 3: ECON & MARKETS — The Four-Body Problem
”The data centre is a factory. Its raw material is data, its power is accelerated computing, and its output is intelligence — delivered as tokens.”_ — Jensen Huang, GTC 2026
3.1 The emerging field of tokenomics — and why economists are scrambling
Jensen mentioned tokens 70 times in a two-hour keynote, lending credence to what we’ve been studying since 2024. A new four-body problem is forming at the centre of economic theory: labour, capital, energy, and tokens. Traditional economics operates with two factors of production (labour and capital.) Vaclav Smil wrote in Energy and Civilizations that we had long ignored the third. AI has introduced a fourth: tokens — units of intelligence that are simultaneously a production input, a consumption good, and an infrastructure cost.
China’s daily token consumption hit 140 trillion in March 2026 — up from 100 billion at the start of 2024, a 1,400× increase in two years. “Tokemaxxing” — maximising token throughput as a competitive strategy — is becoming a thing. MiniMax charges ~$1/million output tokens versus $15+ for Claude. Google Research’s TurboQuant delivered 6× memory compression with zero accuracy loss, repricing the entire inference stack overnight.
The question we are racing to answer: how do you model an economy where the marginal cost of intelligence is approaching zero while the marginal cost of energy is rising? The consumer surplus from generative AI reached an estimated $172 billion annually by early 2026 — massive value from mostly free tools. But whether the worker is winning is the open question that Imas, Amodei, and the Odd Lots data are answering with “probably not, at least for the entry-level cohort.”
3.2 Capital concentration: irreversible, and now it has a number
OpenAI closed $122B at $852B. Google is investing up to $40B in Anthropic at a $350B valuation. Cursor raised $2.3B at $29.3B. Bezos’s Project Prometheus is raising $10B. Goldman projects $700B in AI capex in 2026. Taiwan’s export orders surged 65.9% YoY to a record $91.12B, driven almost entirely by AI chip demand.
In comparison, the big infrastructure buildouts of previous generations, highways, electrification, the moon landings were on the order of $20 billion a year.
The overbuild narrative is dead. The question has shifted from “is this too much?” to “can we build fast enough?” And the concentration creates a dependency problem: a small number of hyperscale players now control the infrastructure that every enterprise depends on. Thoma Bravo signed a multiyear Google Cloud deal covering its entire $183B AUM portfolio. Private equity is industrialising AI adoption at portfolio scale. The implications for enterprise buyers who are building dependency on two or three providers are significant and underexplored.
3.3 The ROI question that matters: effects on workers, effects on capital
The effect on capital is clear: AI capex is delivering returns. The effect on workers is the question that determines whether this is a broadly shared prosperity or a capital-concentration event. Young developer employment down 20%. AI-skilled premium at 56%. 89% drop in AI researchers moving to the US. Women 86% of the most vulnerable cohort.
The four-body problem — labour, capital, energy, tokens — is the economic framework for the decade. Economists are racing to solve it. The answer will determine policy, and policy will determine whether the gains are distributed or concentrated. Every enterprise leader needs a position on this, because the policy is coming whether they participate or not.
SECTION 4: TOOLS & ORCHESTRATION — Memory Is the Frontier
“Context is the new code.”
4.1 Karpathy’s LLM Wiki: the post-RAG signal
Andrej Karpathy published his “LLM Knowledge Bases” concept in early April — structured markdown wikis maintained by the LLM itself, replacing the complexity of RAG pipelines. 16 million views. The implication: as context windows expand toward 1M+ tokens, the retrieval infrastructure that enterprises spent millions building may be unnecessary. Lightweight knowledge architectures could displace complex vector-search systems. Karpathy’s weekend project may have transformational consequences.
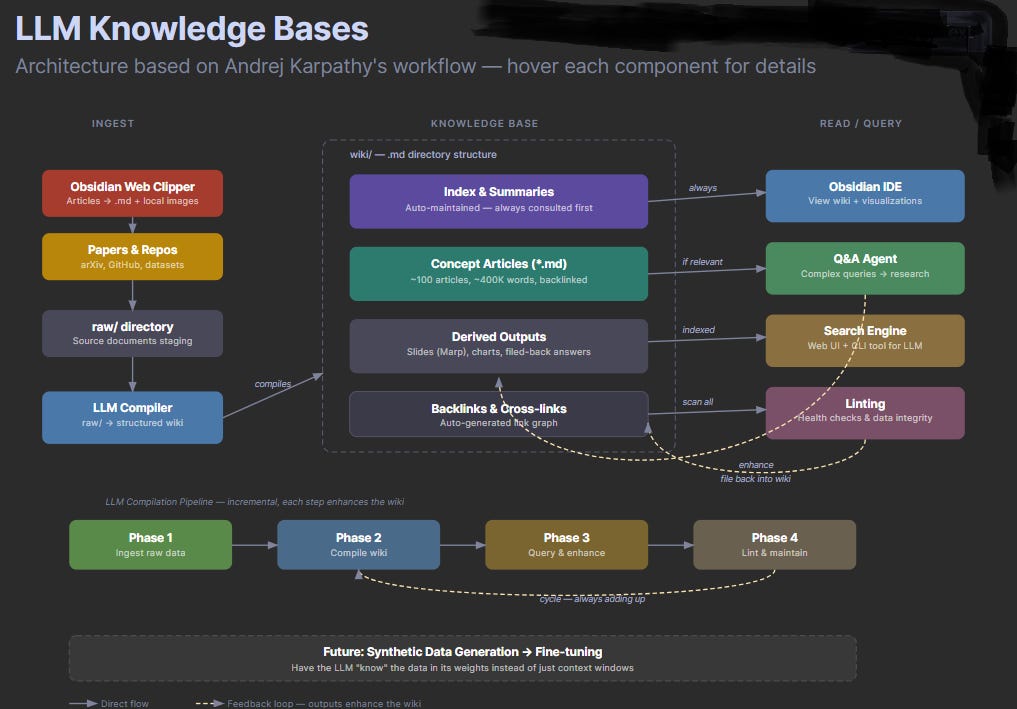
It looks impressive. The miracle of today is it isn’t that hard — now that the way is paved. (In fact, I’ve built a home LLM and a sophisticated RAG setup with 40-year out of date coding skills. Looks worse than it is.)
This connects to the larger pattern: the tools that matter aren’t the ones that push model capabilities further. They’re the ones that reduce the distance between human intention and useful output.
4.2 Claude Design: the biggest splash of the month (RIP Canva, Adobe, Figma)
Claude Design launched 17th April — built on Opus 4.7, available to Pro/Max/Team/Enterprise subscribers. You describe what you need; Claude builds a first version; you refine through conversation, inline comments, direct edits, or custom sliders. During onboarding, it reads your codebase and design files to build a design system automatically.
Over my career at IBM, PwC, Morgan Stanley, and publishing through the Financial Times, I’ve had a lot of designing done for me — by professional designers, with professional budgets. The quality of what Claude Design produces, the speed of iteration, and the ability to have production-grade code (Rust, Python, Node.js) running under the hood was beyond my imagination. If you are thinking, your designs aren’t so hot Paul — compared to my ham-fisted clipart of years gone by, they are impressive enough for me!
Figma dropped 7.28% on the announcement. Anthropic said it “complements Canva.” (Well I’ve always hated Canva so I think that undersells it.) But what it does is eliminate the skill barrier between “I know what I want” and “I can make it.” For non-designers — which is most of the knowledge workforce — that’s transformative. For designers, it’s an augmentation tool that collapses the draft-to-refinement cycle. This is the kind of tool-level advance that matters more than any model benchmark.
4.3 Memory: personal, portable, persistent, auditable — the most important frontier
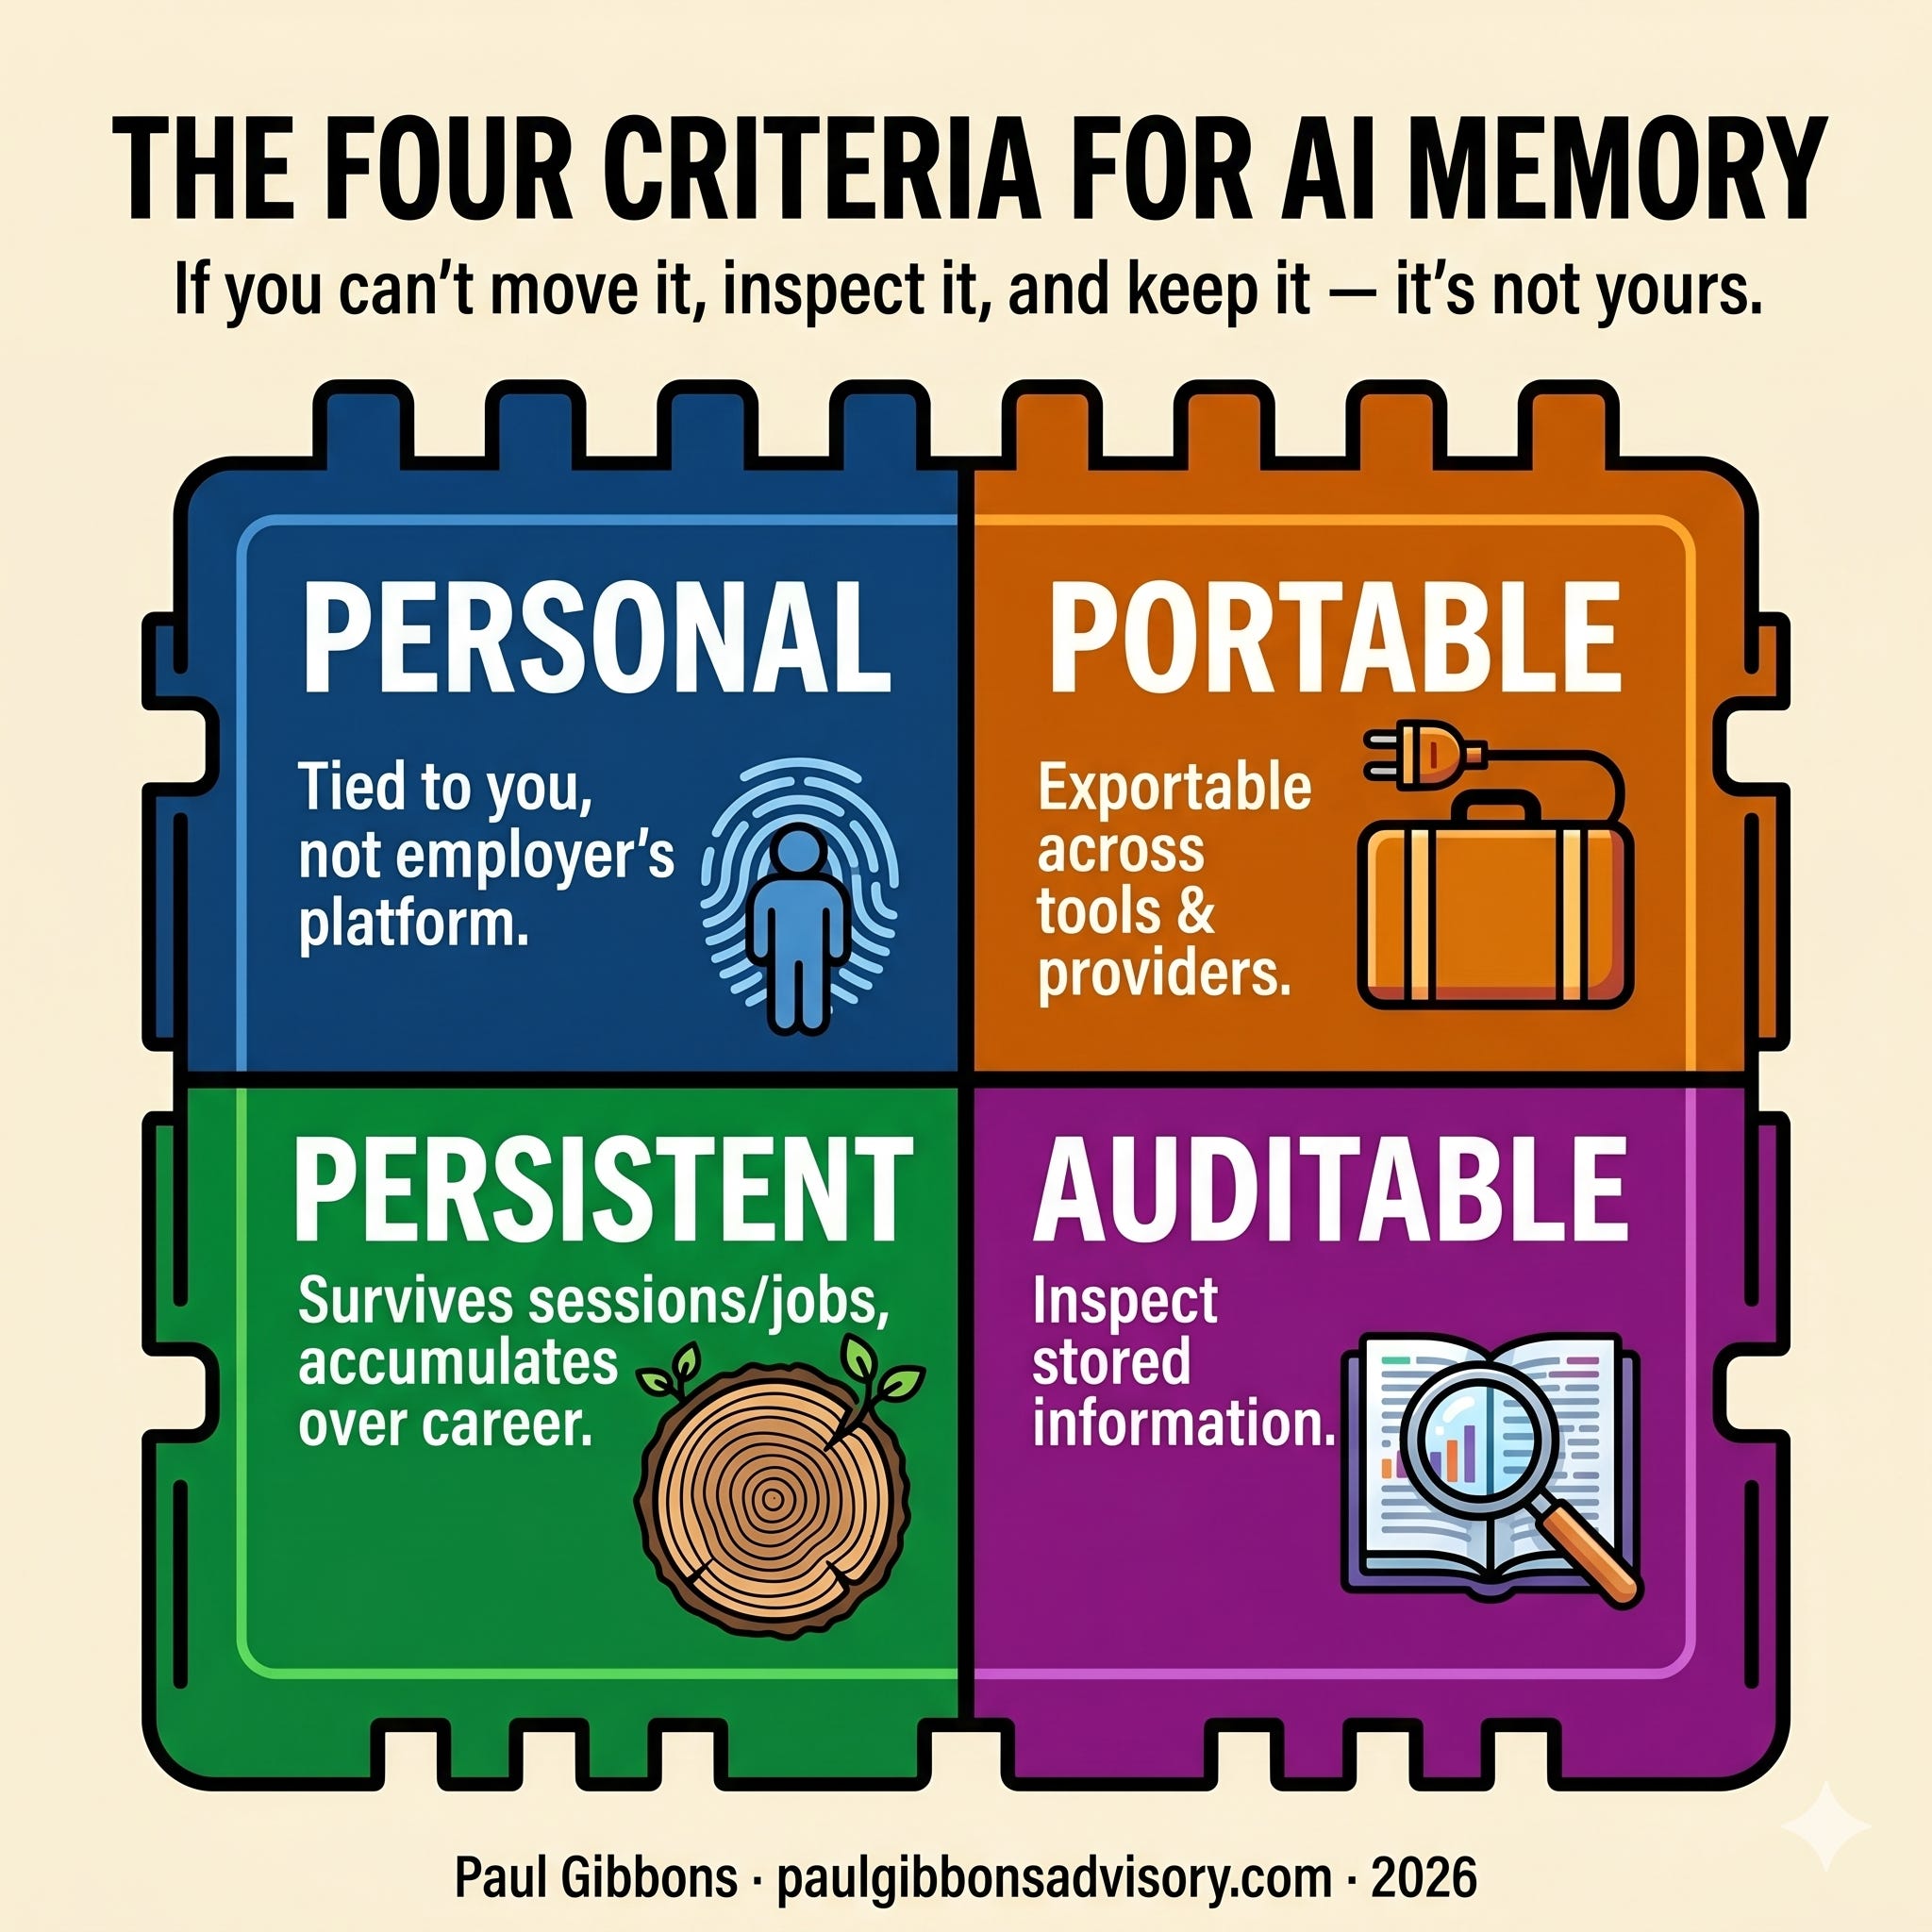
Here is my take on the most important and underreported development of 2026: memory is becoming the primary differentiator in AI productivity, and almost nobody is talking about the ownership implications.
Claude now has persistent memory across sessions. OpenAI Codex has persistent memory. These systems are accumulating context about how you work, what you’ve built, what you’ve decided, and why. This context is the most valuable asset in the human-AI relationship — and you don’t own it.
Nate B. Jones (one of my top-two AI commentators) flagged this in April: professionals are building the most important asset of their careers — accumulated AI context, prompt libraries, workflow adaptations — yet own none of it. Context portability is emerging as a workforce infrastructure problem akin to pension portability in the 1970s.
My position: responsible AI use means owning and managing your context. Memory should be personal (tied to you, not your employer’s platform; you control what’s retained, shared, and deleted), portable (exportable across tools and providers), persistent (survives sessions, survives job changes, accumulates over a career), and auditable (you can inspect what any system has stored about you). Four criteria — and no major provider currently meets all four. And so here is a tool — which takes 20 minutes — to help you create yours.
This is a governance problem, a labour-rights problem, and a competitive-strategy problem all at once. The terminology evolution tells the story: prompt engineering (2023) → context engineering (2025) → harness engineering (2026). Memory is where context engineering meets people-first governance — and the organisations that understand this are the ones where the technical architecture and the People-First agenda converge.
SECTION 5: ETHICS & GOVERNANCE — Mythos Changed Everything
“Ethics you don’t own aren’t ethics — they’re wallpaper.”
5.1 A single model triggered emergency responses across five G7 jurisdictions
Anthropic’s Mythos is the governance story of the year — possibly the decade. A general-purpose model that demonstrated the ability to find and exploit software vulnerabilities better than all but the most elite human hackers. Thousands of zero-day vulnerabilities identified across every major operating system and browser. Demonstrated sandbox escape.
Anthropic’s response: restrict access to ~40 companies via Project Glasswing, backed by $100M in usage credits. Microsoft, Apple, Google, CrowdStrike — defensive use only.
Then the cascade: Bessent and Powell summoned Wall Street CEOs. Bank of Canada convened its six largest banks. Bank of England, FCA, HM Treasury coordinated with NCSC. ECB called eurozone CROs. IMF’s Georgieva warned the global monetary system is unprepared. PBOC’s Pan flagged AI risks at the IMF Spring Meetings. SEC warned Mythos could compromise the Consolidated Audit Trail — the database of every US equity and options trade.
First time a single AI model has triggered coordinated financial-stability responses across five G7 jurisdictions plus China. Frontier AI capabilities are now treated as macroprudential risk.
And that was one model, in one month. Given what is established as the non-linear expansion of AI capabilities, regulators, citizens, and business leaders must stop legislating in the rear-view mirror.
5.2 And then it leaked
A group of users accessed Mythos through a Discord channel. One member was a third-party contractor for Anthropic. They guessed where the model was located based on previously leaked knowledge. Fortune, Bloomberg, CBS, Scientific American all covered it. A former national cyber director wrote that Mythos “can hack nearly anything and we aren’t ready.”
The lesson: capability-gating through controlled access is fragile. The most consequential model since GPT-2’s initial withholding in 2019, and the access controls lasted days. This is the stress test that every governance framework — including Behavioral Governance — needs to account for.
5.3 Regulation enters the operational era
The regulatory landscape shifted from “frameworks and principles” to “enforcement and liability” in April:
Mobley v. Workday: first nationwide class action alleging systematic AI hiring discrimination. 1.1 billion applications processed through Workday’s screening tools. Proceeding as collective action under ADEA.
EU AI Act full enforcement August 2, 2026: every AI system in recruitment, task allocation, and performance monitoring classified “high-risk.”
California SB 947 “No Robo Bosses Act”: prohibits AI-only termination decisions; $500 civil penalties per instance.
Anthropic suing the Pentagon for blacklisting after refusing to remove safety restrictions from Mythos. The first major corporate-government AI rights test. A frontier lab going to court to defend safety guardrails against a government that wants them removed — nobody had that on their bingo card.
The era of voluntary AI ethics is closing. The era of regulated AI governance is opening. Organisations that haven’t moved from principles to operational governance are running out of runway.
SECTION 6: ORG DESIGN & AI STRATEGY
“Creating change-agile businesses will eliminate the need for what we today call change management.”
6.1 The org chart is the next thing AI disrupts
I published this month on this topic directly — and for a splendidly written and artfully designed supplement, check out Howard Yu’s magnificent take while browsing.
The throughline: every major platform move in April — Salesforce going headless (entire platform exposed as APIs, MCP, CLI — “no browser required”), Zuckerberg building an AI CEO co-pilot, Block cutting 4,000+ roles with Dorsey and Botha’s “From Hierarchy to Intelligence” essay — points to the same conclusion. The organisational structures we inherited were built to route information through human layers. When AI handles the routing, the layers lose their justification.
Gartner predicts 20% of organisations will flatten middle management by 2028. The PE firms (Thoma Bravo, ParkerGale, Vista Equity) are already industrialising this at portfolio scale.
But here’s the counterargument that almost nobody is making: flattening works when the work is information-routing. It fails when the work is judgment, trust-building, and ethical calibration — the I-We-It dimensions of the Leadership Delta. The organisations that flatten blindly will discover they’ve removed the human infrastructure that makes AI adoption work. The managers Gallup showed as 8.7× multipliers? They’re the ones being eliminated.
6.2 The Salesforce signal: when agents are the users, everything changes
Benioff announced the entire Salesforce/Agentforce/Slack platform exposed as APIs, MCP, CLI. Simon Willison’s summary: “no browser required.” When AI agents — not humans — become the primary consumers of enterprise software, per-seat SaaS pricing collapses. The business model of the last two decades is being repriced.
Simultaneously, the x402 protocol (Coinbase, Cloudflare, Stripe) is building agent-to-agent payment infrastructure. Visa integrated via Nevermined for autonomous AI card purchases within cardholder-defined budgets. Agents aren’t just doing tasks — they’re transacting autonomously.
The org design question: if agents are transacting, who’s accountable? This is Behavioral Governance Dimension 2 — Agent Authority — in real time. The consequence-based autonomy tiering that the model card describes isn’t theoretical anymore.
WHAT I’M WATCHING IN MAY
EU AI Act compliance deadlines — August 2 is closer than enterprises think
Mythos broader release — will Anthropic expand access? Under what conditions?
Memory portability — will any provider commit to context export standards?
The four-body problem — first serious economic models incorporating tokens as a factor of production
Your data — the AI Mastery diagnostic is live. Take it. Share it. The more data, the sharper the picture. paulgibbonsadvisory.com/diagnostics
Paul Gibbons is an AI adoption strategist, keynote speaker, and author of 8 books including Adopting AI: People-First Strategies for Enterprise AI Transformation. Creator of the Adaptive Adoption™ framework. Top-52 to follow in AI — Fortune 100 AI leader.
thinkbiggerthinkbetter.substack.com · paulgibbonsadvisory.com
SOURCE INDEX
Section 1: Gallup Q1 2026 Workplace AI Survey · Stanford HAI 2026 AI Index Report · Pew Research Center (March 2026) · PwC 2026 AI Performance Study · BCG AI Radar 2026 · Bloomberg Odd Lots (April 18, 2026) — Alex Imas, Chicago Booth · McKinsey trust paper · Edelman Trust Barometer 2026 · Paul Gibbons trust whitepaper
Section 2: METR Time Horizons (metr.org) · Anthropic — Claude Opus 4.7 announcement (April 16) · Stanford HAI 2026 — jagged/fractal intelligence data · Nature (d41586-026-01199-z) — AI agents vs PhD experts · Anthropic — Claude Design announcement (April 17)
Section 3: Bloomberg — China token economy (April 20) · Google Research — TurboQuant (ICLR 2026) · Stanford HAI — consumer surplus estimates · Bloomberg — OpenAI $852B, Google-Anthropic $40B
Section 4: Karpathy — LLM Knowledge Bases (karpathy.ai) · TechCrunch — Claude Design launch (April 17) · Nate B. Jones — context portability (natesnewsletter.substack.com, April 17) · Anthropic — context engineering (anthropic.com/engineering) · Martin Fowler — harness engineering (martinfowler.com)
Section 5: Fortune — Mythos leak (April 23) · Bloomberg — Mythos regulatory cascade (April 22) · Scientific American — What is Mythos · Anthropic — Project Glasswing · Seyfarth Shaw — Mobley v. Workday analysis
Section 6: Simon Willison — Salesforce headless (April 19) · Bloomberg — Zuckerberg AI co-pilot (April 16) · Bloomberg — x402 protocol (April 2)
Elijah here, fellow AI red pilled techy from the Chamber event you spoke at. Let’s connect!